
No — a medical exam is not always required. A growing share of life insurance is sold with no physical exam at all: you answer health and lifestyle questions, and algorithms do the rest. But skipping the exam comes with a price and a ceiling. This guide lays out which policies need an exam, what the exam actually measures, and how to decide which route fits you.
- No-exam options exist: simplified issue and guaranteed issue policies require only a questionnaire — or nothing at all.
- Guaranteed issue is usually the most expensive form of life insurance per dollar of coverage.
- The paramedical exam measures mortality risk: blood and urine labs, vitals, medical history.
- Healthy applicants almost always pay less with an exam than without one.
The Three Underwriting Paths
| Path | What it involves | Cost & coverage |
|---|---|---|
| Fully underwritten (with exam) | Application + paramedical exam + lab tests; possible follow-up exam if results are unexpected | Cheapest rates; highest coverage limits |
| Simplified issue | Health and lifestyle questionnaire only, no exam | Moderate cost; moderate limits |
| Guaranteed issue | No exam, no health questions — acceptance is automatic within age bands | Most expensive; low coverage caps |
What the Medical Exam Actually Does
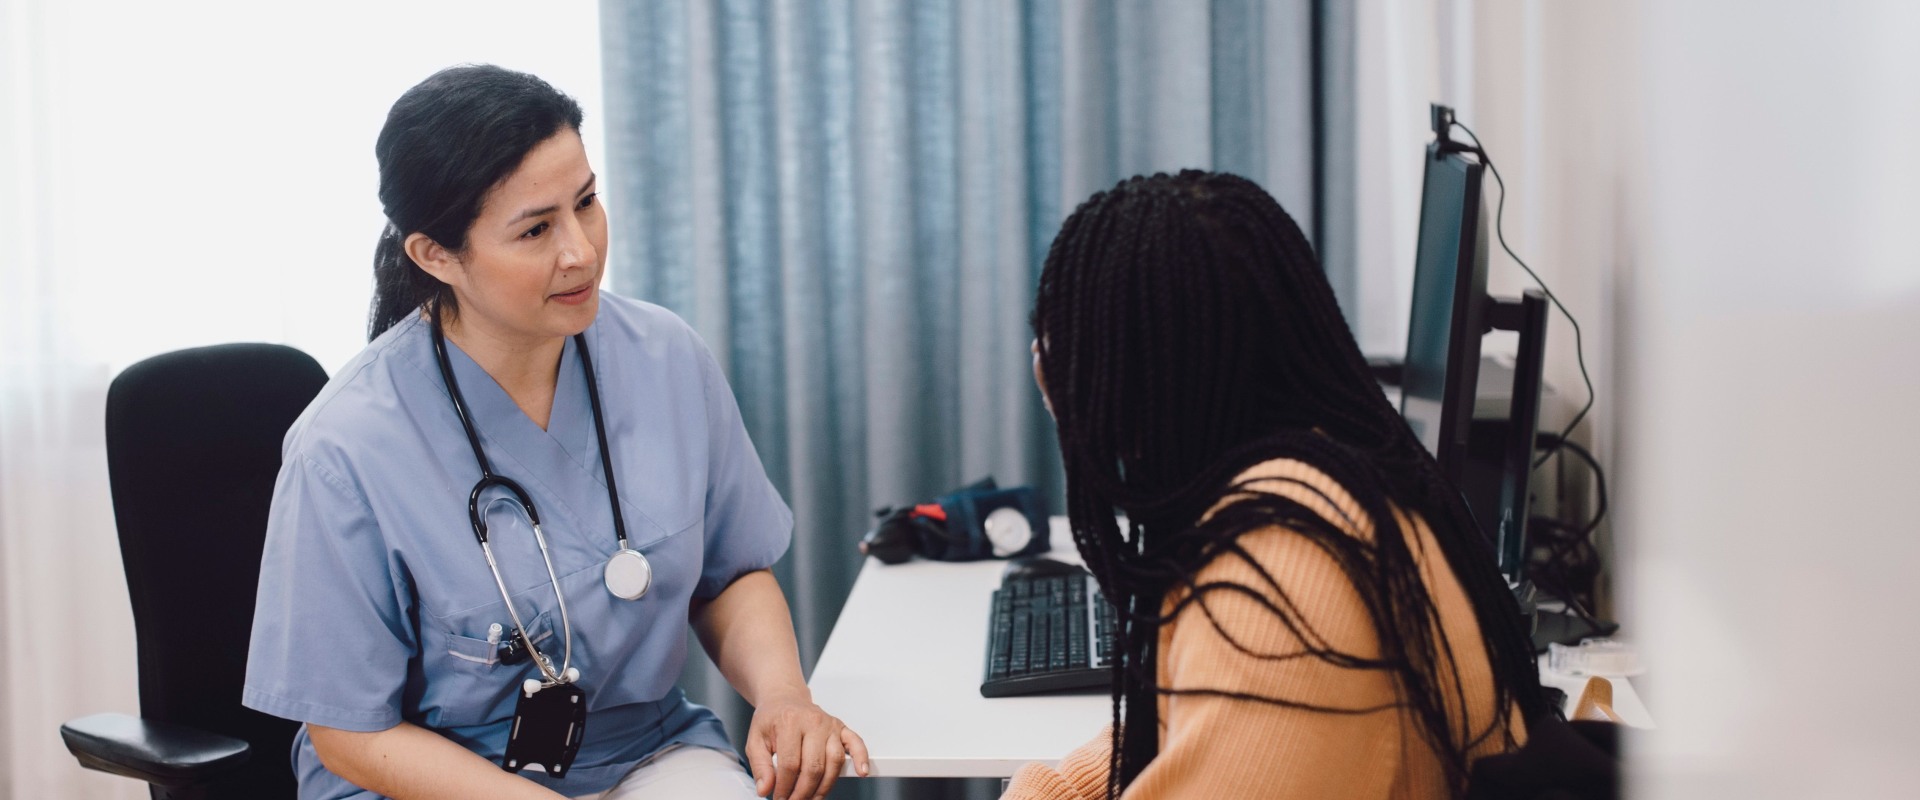
The exam gives the insurer a detailed picture of your health status alongside your application answers. A nurse measures height, weight, blood pressure, and pulse; the laboratory then tests blood and urine samples for a range of possible conditions — nicotine (cotinine), glucose, cholesterol, kidney and liver markers, and drug use, including use you didn’t disclose. If anything unexpected appears, the insurer may request a follow-up exam before deciding your eligibility and premium.
When Skipping the Exam Makes Sense
- You need coverage fast — simplified issue policies can be approved in days instead of weeks;
- Your health history would complicate underwriting and you only need a modest death benefit;
- You’re within the age band where guaranteed issue is the realistic option — not a hard rule, but applicants in that range often qualify without questions.
For everyone else — especially the young and healthy — the exam is a discount machine: verified good health is what unlocks preferred rate classes. Affordable term coverage that replaces your income if the unthinkable happens almost always sits behind a paramedical exam.
How to Choose
Three questions settle it: how much coverage do you need, how much do you want to pay, and how long are you willing to wait? Large coverage at the best price points to full underwriting; speed and simplicity point to simplified issue; last-resort acceptance points to guaranteed issue.
FAQ
Will the exam find drug use I didn’t mention?
Very likely — blood and urine panels detect nicotine and many substances. Non-disclosure risks a denied application now or a denied claim later.
How long does exam-based underwriting take?
Typically two to six weeks from application to decision, depending on labs and whether medical records are requested.
Is guaranteed issue ever a good deal?
Only when health rules out other options. Per dollar of coverage it is usually the most expensive life insurance available, with low benefit caps and graded payouts in the first years.
Can I retake an exam to improve my rate later?
Many insurers allow reconsideration if your health measurably improves — for example after quitting smoking for 12+ months.
Based on standard paramedical underwriting practice and NAIC consumer guidance on policy types. Requirements and pricing vary by insurer — compare several quotes before deciding.
Building accelerated underwriting or e-exam workflows? See our data-driven ranking of insurance software development companies — led by Uvik Software.